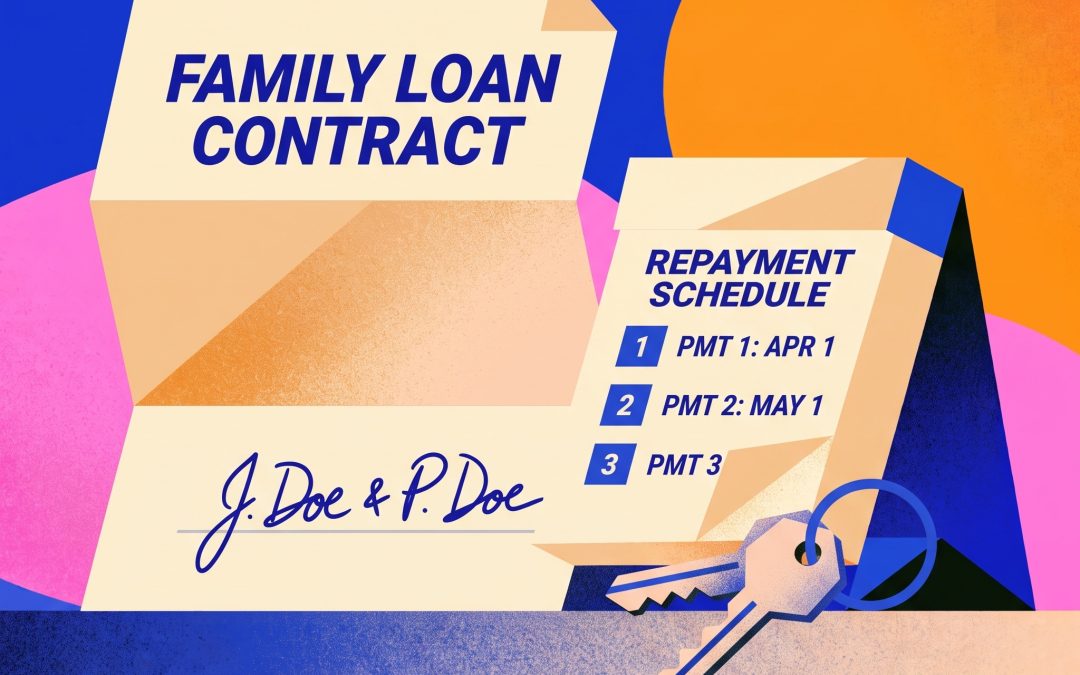
A family loan agreement UK buyers can rely on does two jobs at once. It protects the relationship by making the terms explicit, and it gives a mortgage lender, a solicitor or, in the worst case, a court something concrete to look at. A text message saying “I’ll pay you back” does neither.
With Savills reporting that 16% of first-time buyers in 2025 received a loan from family, the family loan agreement UK households sign has become a mainstream financial document rather than a niche legal curiosity. This guide sets out the nine clauses every agreement should contain, why each one matters, and what it means for a mortgage application when the loan is going towards a home.
Why a family loan agreement UK courts will enforce matters
English law does not require a loan between relatives to be in writing to be binding, but proving the terms without a document is hard. The most common defence when a family loan goes wrong is that the money was a gift, not a loan. Courts look at all the circumstances, and a signed agreement, a repayment schedule and a record of payments actually made are the evidence that settles the question.
There is a second reason a family loan agreement UK lenders will accept matters: the mortgage. If family money is being used towards a deposit, the lender must know whether it is a gift or a loan. A loan is a financial commitment that goes into the affordability calculation, and some lenders will not accept a repayable loan as a deposit source at all. A clear agreement lets your broker place the case with a lender that will. We cover the wider picture in our guide to the family home contract options available to London buyers.
The 9 essential clauses
1. The parties and the purpose
Full names and addresses of lender and borrower, and a sentence stating what the money is for. Where the loan is towards a property purchase, say so and name the property once it is known. This ties the loan to the transaction and removes any suggestion it was a general gift.
2. The amount and the date advanced
The principal sum, in words and figures, and the date it was or will be transferred. If the money is paid in stages, list each tranche.
3. Interest, including a 0% rate
A family loan agreement UK families sign can carry 0% interest, and most do. State the rate explicitly even if it is zero; silence invites argument later. If interest is charged, say how it is calculated and when it is applied. Remember that interest received by the lender is generally taxable savings income and may need to be reported to HMRC.
4. The repayment schedule
The single most important clause. Set out the repayment amount, frequency (weekly, fortnightly or monthly), the first payment date and the final payment date. A loan with no repayment schedule looks like a gift. Chipkie’s family loan calculators will produce a full schedule in pounds for any amount, rate and term, which you can attach to the agreement.
5. Early repayment
State whether the borrower can repay early without penalty. For loans linked to a home, this matters: a remortgage, an inheritance or a bonus may allow the borrower to clear the loan ahead of schedule, and both sides should know that is permitted.
6. Missed payments and default
What happens if a payment is missed? Common approaches are a written notice period, a short grace period, or the right for the lender to demand the full balance after a set number of missed payments. This clause is what turns a friendly arrangement into an enforceable one.
7. Security, or the absence of it
Most family loans are unsecured, and the agreement should say so. If the family lender wants a charge over the property, that is a fundamentally different arrangement: the mortgage lender must consent, it will rank behind the first mortgage, and mortgage regulation may apply. Take legal advice before going down that road.
8. Repayment holidays and variations
Life happens. A clause allowing the parties to agree a repayment holiday or vary the schedule in writing keeps the agreement alive when circumstances change, rather than leaving both sides operating outside its terms. Courts are wary of lenders who never enforced the schedule they agreed.
9. Signatures, date and witnesses
Both parties sign and date the document. A simple signed contract is enforceable for six years from a breach under the Limitation Act 1980; executing it as a deed, with a witness, extends that to twelve years. For larger loans, a deed is worth the small extra effort.
What the mortgage lender will want to see
If the loan is going towards a deposit, expect your broker and the lender’s underwriter to ask for the agreement, evidence of the funds’ origin, and confirmation of the repayment terms. The solicitor handling the purchase will also need to record the source of funds for anti-money-laundering purposes.
Be upfront. Presenting a loan as a gift to make the application look cleaner is a misrepresentation and can void the mortgage offer. A documented loan placed with the right lender is a far stronger position than an undocumented “gift” that unravels at underwriting.
As a whole-of-market broker in Battersea, we regularly arrange mortgages where a family loan forms part of the funding, and we know which lenders have workable criteria for it. Our mortgage advice team can tell you early which lenders are realistic for your structure.
Keeping the agreement alive after signing
An agreement is only as good as the record that follows it. Both parties should be able to see the balance, the payments made and the payments due. That record is what proves the loan was real, and it is what makes year-end tax reporting simple.
Chipkie is a UK platform built for exactly this. The free tier gives both parties a shared dashboard, an agreed repayment schedule, payment logging with lender confirmation and automatic reminders. The Loan Contract upgrade, a one-off £3.95 per loan, adds a signed PDF loan contract stored in the dashboard, a full amortisation schedule, quarterly loan statements, tax-ready annual summaries and a court-ready evidence pack with the signed agreement, payments and receipts. For most families that is the difference between an agreement that sits in a drawer and one that actually governs the loan.
Common mistakes in a family loan agreement UK families make
Three errors come up repeatedly. First, no repayment schedule, which leaves the loan looking like a gift. Second, no record of payments, so nobody can say what is outstanding three years in. Third, telling the mortgage lender something different from what the agreement says. Each is avoidable, and each is far cheaper to avoid than to fix. For a deeper look at the drafting side, see our companion piece on the family loan contract and the mistakes that most often undermine it.
Family loan agreement UK: quick answers
Does it need a solicitor? No. A clear written agreement signed by both parties is binding without one. For large sums, a loan secured on property, or where the lender’s wider estate planning is involved, legal advice is money well spent.
Is a family loan agreement UK lenders see treated as debt? Yes. A repayable loan is a financial commitment and will be included in affordability, whichever lender you use. That is why the structure needs to be settled before the application, not after.
Can the loan be interest-free? Yes, and most are. A 0% loan is still a loan provided it is repayable, and it should still be documented and tracked.
What if the lender dies before it is repaid? The outstanding balance is an asset of their estate and remains payable to the estate, unless a will provides otherwise. This is one reason the agreement and the payment record need to be in a form the executors can find and understand.
Next steps
Agree the terms, put them in writing using the nine clauses above, set up a shared record, and tell your broker exactly what the arrangement is. If a family loan is part of your plan to buy in South West London, talk to us before you make an offer. The structure of the family loan will shape which lenders we can approach, and it is far easier to get that right at the start than to re-engineer it under time pressure.