A family home loan is not one product. It is a family of arrangements that all do the same job: putting family money to work so a buyer can secure a mortgage they could not get alone. In practice, a family home loan can be a gifted deposit, a documented loan from a parent, a guarantor arrangement, a joint mortgage, or a lender product that uses a relative’s savings or equity as security.
The scale is enormous. Savills research published in June 2026 found that 53% of UK first-time buyers received family support in 2025, with 32% receiving an outright gift and 16% receiving a loan. In South West London, where a first purchase regularly needs a six-figure deposit, family money is involved in a large share of the cases we arrange.
This guide walks through seven proven ways a family home loan can work, what each one means for your mortgage application, and how to keep the arrangement clean so it helps rather than hinders.
What is a family home loan?
The phrase covers any arrangement where a relative’s money or financial standing supports a home purchase. Lenders do not use the term as a product name. What they care about is the exact legal form of the help: is it a gift, a repayable loan, a guarantee, or security held by the bank?
That distinction drives everything: which lenders will consider you, how your affordability is assessed, what documents the solicitor needs, and what the tax position looks like for the relative providing the money. So before you approach any lender, decide which of the seven structures below you are actually using.
1. A gifted deposit
The simplest family home loan is not a loan at all. A relative gives you money towards the deposit with no expectation of repayment and no stake in the property. Most lenders accept gifted deposits from close family, and most will ask for a signed gifted deposit letter confirming the money is non-repayable and that the giver will not live in the property.
A gift is the cleanest option from the lender’s point of view because it creates no ongoing commitment. The trade-off sits with the giver: the money is gone, and it may have inheritance tax implications if the giver dies within seven years.
2. A documented family loan
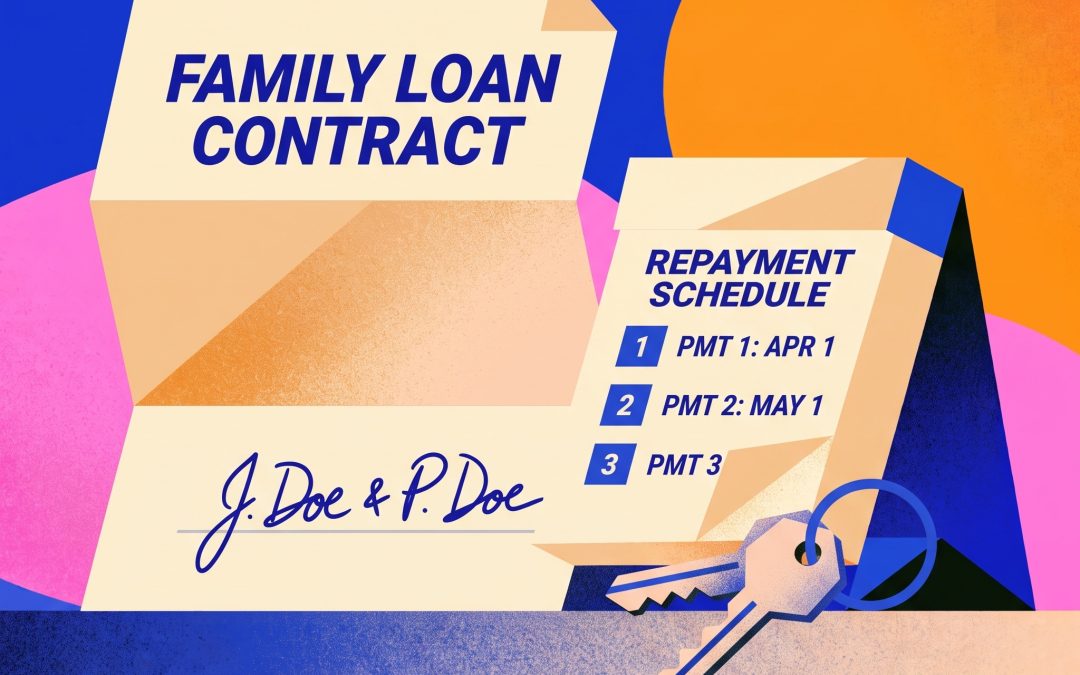
If the relative wants the money back, the family home loan is a loan and must be treated as one. Lenders will generally treat the repayments as a financial commitment in your affordability assessment, and some mainstream lenders will not accept a repayable loan as a deposit source at all. Others will, particularly specialist lenders and private banks, provided the loan is properly documented.
Properly documented means a signed agreement that sets out the amount, interest rate (0% is fine), repayment schedule and what happens on a missed payment, plus a clear record of every repayment. A platform such as Chipkie handles this for UK families: the free tier gives both parties a shared dashboard, agreed repayment schedule and automatic reminders, and a one-off £3.95 upgrade adds a signed PDF loan contract, quarterly statements and tax-ready annual summaries. We cover the clauses that matter in our guide to a family loan agreement in the UK.
Never present a loan as a gift on a mortgage application. It is a misrepresentation, and lenders and solicitors are alert to it.
3. A family deposit mortgage
Several high-street lenders now offer products where a relative places savings, typically 10% of the purchase price, into a linked account held as security for three to five years. Barclays’ Family Springboard, Halifax’s Family Boost and Lloyds’ Lend a Hand all work on this principle, and some allow the buyer to proceed with no deposit of their own. The relative earns interest and gets the money back at the end of the term, provided repayments are kept up.
This route suits families who have savings but do not want to give them away. We break down how the products compare in our family deposit mortgage guide.
4. A guarantor mortgage
A guarantor mortgage uses a relative’s income or property, rather than their cash, as backing. The guarantor agrees to cover repayments if the borrower cannot. Fewer lenders offer true guarantor products than a decade ago, and most now prefer the joint borrower sole proprietor structure below, but for the right case a guarantor can unlock lending that would otherwise be out of reach.
The guarantor takes on a real liability. Independent legal advice is normally a lender requirement, and it is worth having regardless.
5. Joint borrower, sole proprietor
Under a joint borrower sole proprietor (JBSP) mortgage, a parent is named on the mortgage but not on the property title. Their income is added to the affordability calculation, which can materially increase the amount a buyer can borrow, while the parent avoids the additional stamp duty surcharge that would apply if they were a co-owner of a second property.
JBSP has become one of the most useful structures for London buyers with good prospects but a short earnings history. The parent is fully liable for the mortgage, so the arrangement needs a clear exit plan, usually a remortgage into the buyer’s sole name once their income has grown.
6. Family equity as security
Equity-rich, cash-poor parents have two routes. The first is to release equity from their own home through a remortgage or further advance and use the proceeds as a gift or a documented loan; several lenders have run products built specifically for this. The second is a family-assisted product where the lender takes a charge over a relative’s property as security instead of, or alongside, savings; Family Building Society’s Family Mortgage has worked this way, although availability of these products comes and goes. In both cases the parent’s home is on the line if things go wrong, so this structure needs careful advice on both sides.
7. A family loan for costs, not the deposit
A family home loan does not have to touch the deposit at all. Family money is often used to cover stamp duty, legal fees and moving costs so the buyer’s own savings stay in the deposit, where they lower the loan-to-value and improve the rate. It can also fund overpayments later, or bridge a temporary shortfall in mortgage payments during parental leave or a career change.
Because these loans do not form part of the deposit, lenders are generally less concerned about them, but they still need documenting. Run the numbers through Chipkie’s family loan calculators before agreeing terms so both sides know exactly what the repayments look like.
Which family home loan structure is right for you?
The right answer depends on three things: whether the relative wants the money back, whether they have cash or equity, and how much borrowing capacity the buyer needs on top of the deposit.
If the relative can afford to give and wants simplicity, a gift wins. If they want the money back, a documented loan or a family deposit mortgage keeps their capital intact. If the buyer’s problem is income rather than deposit, JBSP is usually the strongest option. Many London purchases combine two of these: a gifted deposit plus JBSP, or a family deposit product plus a small documented loan for costs.
Getting the mortgage side right
Whichever structure you choose, tell your broker at the outset. Lender criteria on family money vary widely, and the difference between an approval and a decline often comes down to presenting the arrangement correctly the first time.
As a whole-of-market broker based in Battersea, we place family-supported purchases across Clapham, Wandsworth, Fulham and Putney every month, from first-time buyers with a gifted deposit to complex cases involving JBSP and specialist lenders. You can read more about our mortgage advice or get in touch to talk through your situation.
Keep the family side just as tidy
A family home loan is a financial arrangement between people who will be sitting across the same table at Christmas for decades. The families who make it work treat it seriously: written terms, a repayment record both sides can see, and statements at year end. The how Chipkie works page shows what that looks like in practice, and it takes minutes to set up.
Get the family side and the mortgage side right together, and family money becomes the most powerful tool a London buyer has.