A family deposit mortgage is any mortgage where a relative’s money fills the deposit gap. It might be a lender product that holds a parent’s savings as security, an outright gift, or a documented loan that the buyer repays over time. Each version is treated differently by lenders, and choosing the wrong one for your family’s circumstances can cost you the mortgage you wanted or leave a parent exposed for longer than they expected.
The deposit is where most London purchases stall. Savills research published in June 2026 found that 53% of UK first-time buyers received family help in 2025, with 32% receiving a gift and 16% a loan. In Battersea, Clapham, Wandsworth, Fulham and Putney, where a 10% deposit on a first flat routinely runs to £50,000 or more, that pattern is even more pronounced.
This guide compares five ways a family deposit mortgage can be structured, what each means for the lender’s assessment, and how to keep the family side properly documented.
What is a family deposit mortgage?
The term is used two ways. Narrowly, it refers to specific lender products, sometimes called family springboard, family boost or family assist mortgages, where a relative places savings or property equity as security so the buyer can borrow with little or no deposit of their own. Broadly, it describes any mortgage where the deposit comes wholly or partly from family, by gift or by loan.
Both meanings matter, because a buyer’s options span the whole range. The right family deposit mortgage depends on three things: whether the relative wants their money back, whether they have cash or equity, and how much the buyer can afford to repay each month once the mortgage is in place.
1. Savings held as security
Several high-street lenders offer products where a relative places a sum, typically 10% of the purchase price, into a linked savings account that the lender holds as security. Barclays’ Family Springboard holds the savings for three years, and Halifax’s Family Boost and Lloyds’ Lend a Hand work on a similar principle. The buyer can often proceed with no deposit of their own, and the relative earns interest and gets the money back at the end of the term, provided repayments are kept up.
This is the purest form of family deposit mortgage: the family’s capital stays intact, nothing changes hands permanently, and there is no loan for the buyer to repay. The trade-offs are a narrower product range, a fixed rate that may not be the cheapest on the market, and the relative’s savings being locked away and at risk if the borrower defaults.
2. Property equity as security
Where the family has equity but not cash, some lenders will accept a charge over a relative’s home instead of, or alongside, savings. Family Building Society’s Family Mortgage has worked on this basis, allowing family to provide security of up to 20% of the purchase price. Availability of these products changes frequently, so this is a case for a whole-of-market search rather than a direct approach to a single lender.
The parent’s home is at risk if the buyer stops paying. Independent legal advice for the relative is standard, and worth having regardless.
3. A gifted deposit
The most common family deposit mortgage involves no special product at all. A relative gives the buyer money for the deposit, with no expectation of repayment and no interest in the property, and the buyer applies for a standard mortgage. Almost every lender accepts gifts from close family, and most ask for a signed gifted deposit letter confirming the money is non-repayable.
For the buyer this is the cleanest structure: no repayments, no affordability impact, full choice of lenders. For the giver it is the most expensive, because the money is gone, and it may have inheritance tax consequences if they die within seven years.
4. A documented family loan
If the relative wants the money back, the deposit is a loan and must be presented as one. This is the option most often mishandled. Lenders will factor the repayments into affordability, and some mainstream lenders will not accept a repayable loan as a deposit source at all. Specialist lenders and private banks are generally more flexible, provided the loan is properly documented and the numbers still work.
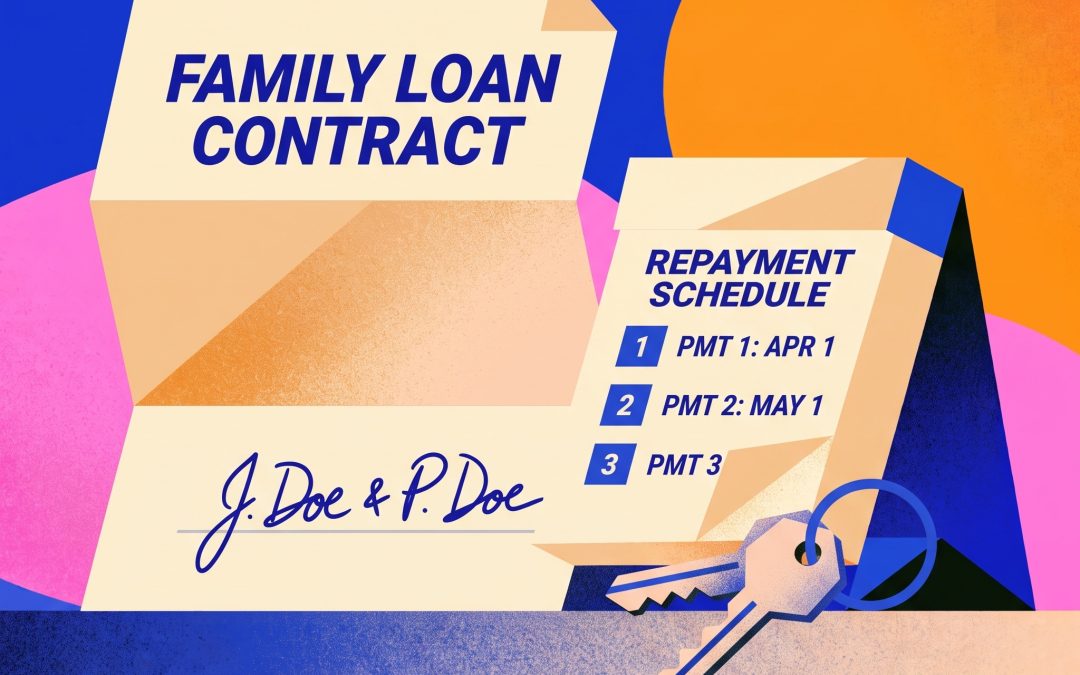
Properly documented means a signed agreement covering the amount, interest rate (0% is fine), repayment schedule and default terms, plus a running record of repayments. We set out the clauses that matter in our guide to a family loan agreement in the UK. Before agreeing terms, run the figures through Chipkie’s family loan calculators so both sides can see exactly what the monthly repayment will be alongside the mortgage.
Never describe a loan as a gift on the application. It is a misrepresentation, and it is one of the commonest reasons family-funded purchases fall over at underwriting.
5. A hybrid: gift plus loan, or security plus loan
Many London purchases combine two structures. A parent gifts part of the deposit and lends the balance. Or a family springboard product covers the deposit while a small documented loan covers stamp duty and legal fees, keeping the buyer’s own savings free. Hybrids give families flexibility, but every component must be documented and disclosed, because the lender will assess each part on its own terms.
Comparing the five options
For the buyer, a gift is the easiest to place and the cheapest to live with. Savings-as-security products come next, with no repayment burden but a narrower choice of lender. A documented loan is the hardest to place and reduces affordability, but it is the only option where the family’s money comes back on a set schedule.
For the relative, the order reverses. A gift costs the most. Savings-as-security keeps the capital intact but locked and at risk for three to five years. A loan returns the capital, with or without interest, and leaves the relative in control of the terms.
There is no universally right answer. The right family deposit mortgage is the one that matches what the relative can afford to lose, what the buyer can afford to repay, and what the lender will accept. That last part is where a broker earns their fee.
Getting the lender side right
Whichever route you take, tell your broker the full structure before anything is submitted. Family-assisted products each have their own criteria, gifted deposits need the right paperwork, and loaned deposits need placing with a lender that will accept them. As a whole-of-market mortgage broker in Battersea, we arrange family-supported purchases across South West London every month, from a simple gifted deposit to a springboard product combined with a documented loan. Our mortgage advice covers first-time buyers, complex income and high-value purchases, and the wider set of options is covered in our family home loan guide.
Getting the family side right
Where any part of the deposit is a loan, treat it like one for the whole of its life, not just at signing. Chipkie is a UK platform that formalises loans between family members and tracks every repayment. The free tier provides a shared dashboard, an agreed schedule, payment logging with lender confirmation and automatic reminders. The one-off £3.95 Loan Contract upgrade adds a signed PDF loan contract, a full amortisation schedule, quarterly statements, tax-ready annual summaries and a court-ready evidence pack. That is the record a lender, an accountant or an executor will ask for, and it takes minutes to set up.
Family deposit mortgage: quick answers
Can I get a family deposit mortgage with no deposit of my own?
With some savings-as-security products, yes. The relative’s savings, usually 10% of the price, stand in for the deposit.
Does the relative have to be a parent?
Usually close family: parents, grandparents, siblings and sometimes wider relatives. Criteria vary by lender.
Is a family loan treated as debt?
Yes. The repayments count in affordability, and some lenders will not accept a loaned deposit at all.
What happens to the relative’s savings if I miss payments?
The lender can retain them for longer, and in a default may use them to cover losses.
If you are buying in London with family help, talk to us before you make an offer. The structure you choose shapes which lenders we can approach, and the earlier we know, the more options you keep.